Tag Archive for: south carolina insurance

Older Homes Need Love Too: Understanding Insurance Options for Aging Homes

Older homes have a charm and character that newer homes simply can’t replicate. From beautiful hardwood floors and unique architectural details to the stories held within their walls, many South Carolina homeowners are proud to own a piece of history.

 But when it comes to insurance, older homes can present unique challenges.

 At Carolina Property Insurance, one of the most common questions we hear is:

“Why is my home more expensive to insure?”

There are several factors that are considered when building rates for homes that are not new construction.

Why Are Older Homes Different?

Insurance companies look at risk when evaluating any property. Age of the home is the foundation of the rate on your home. While older homes offer plenty of charm and character, they may not have been built to the same wind-resistant standards required for newer homes today.

With older homes, they often pay closer attention because key systems may be approaching the end of their useful life.

Some of the items carriers may review include:

  • Roof age and condition
  • Electrical systems and wiring
  • Plumbing systems
  • HVAC systems
  • Foundation and structural integrity
  • Previous renovations and upgrades

Even well-maintained homes may require additional inspections simply because of their age. Some carriers may request a 4-point inspection or other documentation to verify that major systems have been updated.

What Makes an Older Home More Attractive to Insurance Companies?

Age alone doesn’t necessarily make a home uninsurable.

Many older homes qualify for excellent coverage when they have been properly maintained and updated. Insurance companies often look favorably on homes with:

  Updated roofing

 Modern electrical systems

 Updated plumbing

 Newer HVAC systems

 Renovations that improve safety and reduce risk

 The more documentation you have regarding upgrades and improvements, the easier it may be to find coverage options and take advantage of important discounts.

Tips for Homeowners with Older Homes

 If you own an older property, consider these steps:

  • Keep records of all renovations and improvements.
  • Schedule regular maintenance inspections.
  • Address aging electrical or plumbing issues promptly.
  • Replace aging roofs before problems develop.
  • Review your insurance coverage annually.


Let Carolina Property Insurance Help

Every older home has its own story, our team understands that no two properties are exactly alike.

At Carolina Property Insurance, we work with multiple insurance carriers and can help you explore available coverage options based on your home’s age, condition, and updates. We ask questions and look for ways to save you money on your annual insurance costs.

Contact Carolina Property Insurance today for a personalized review and let our team help you find coverage designed to protect the home you’ve worked hard to maintain.
Peak Hurricane Season: Are You Prepared? 

Peak Hurricane Season: Are You Prepared?

As we move into the peak of hurricane season, now is the time to make sure your family, home, and insurance coverage are ready before a storm develops. Living along the South Carolina coast means preparing for more than just wind. Heavy rain, flooding, power outages, and storm-related damage can impact communities throughout Murrells Inlet, Myrtle Beach, and beyond.

At Carolina Property Insurance, we encourage homeowners to take a few simple steps now to help protect what matters most:

✅ Refresh your emergency kit with food, water, medications, batteries, and important supplies.
✅ Secure important documents and create digital backups.
✅ Take photos of your home and belongings for insurance records.
✅ Prepare your property by securing outdoor items and addressing maintenance concerns.
✅ Know your evacuation zone and have a family communication plan in place.
✅ Review your homeowners and flood insurance coverage before a storm is approaching.

One of the biggest misconceptions we see is that all hurricane-related damage is covered by a standard homeowners policy. Coverage varies by carrier and flood insurance is often purchased separately, making it important to understand your protection before severe weather threatens our area.

Hurricane preparedness isn’t about expecting the worst. It’s about having a plan and the right coverage in place so you can weather the storm with greater confidence.

Not sure if your coverage is storm-ready? Contact Carolina Property Insurance today for a complimentary policy review and let our team help you prepare for the rest of hurricane season.

Living on the Coast? The Hurricane Insurance Myth We Hear Most

Living on the Coast? The Hurricane Insurance Myth We Hear Most

One of the most common insurance myths we hear from coastal homeowners is: “My homeowners policy covers flooding.” In most cases, that is not accurate.

Why Homeowners Insurance Usually Does Not Cover Flooding

Standard homeowners policies generally exclude damage caused by rising water, which is considered flood. Some policies may allow flood coverage to be added by endorsement, but many carriers in our coastal area do not offer that option on a standard homeowners policy.

For most homeowners, the best way to protect against flood damage is to purchase a separate flood insurance policy.

How Homeowners Insurance Typically Defines Flood

From a homeowners insurance standpoint, flood usually means water that comes from outside the home and rises from the ground up. This is often referred to as “rising water.”

How Flood Insurance Typically Defines Flood

Flood insurance commonly defines a flood as a general and temporary condition where rising water inundates either:

  • Two or more acres of normally dry land; or
  • Two or more properties, including the insured property.

This can include overflow of inland or tidal waters, heavy rain accumulation, storm surge, or mudflow.

If a Hurricane Causes Flooding, Will My Homeowners Policy Pay?

Not necessarily. This is another common misconception. Even if a named storm brings heavy rain or storm surge, the claim is still adjusted based on the cause of loss. If the damage is caused by rising water, it is treated as flood damage.

Because flood is typically excluded from a homeowners policy, that damage would not be covered unless flood coverage was specifically added by endorsement or protected through a separate flood insurance policy.

Bottom Line for Coastal Homeowners

If you live near the coast, do not assume your homeowners policy covers all hurricane-related damage. Wind, rain, and flood can be treated differently by insurance companies, so it is important to review your policy and consider separate flood coverage before storm season.

Submitted by- Mary Beth Morris

Does Auto Insurance Follow the Car or the Driver?

One of the most common questions we hear at Carolina Property Insurance is: “If I lend my car to someone, will my insurance cover them?” The answer is usually yes—but there are important exceptions every driver should understand.

Knowing how auto insurance applies when someone else is behind the wheel can help you avoid costly surprises and make informed decisions about who drives your vehicle.

In Most Cases, Insurance Follows the Vehicle

Generally, auto insurance is attached to the vehicle, not the person driving it. If you allow a friend or family member to borrow your car and they’re involved in an accident, your policy is typically the first line of coverage.

This means your liability coverage may help pay for injuries or property damage caused by the accident, up to your policy limits.

If damages exceed those limits, the driver’s insurance policy may provide additional coverage. That’s why having adequate liability protection is so important.

When Coverage May Not Apply

While insurance often follows the vehicle, there are situations where coverage could be limited or denied:

Permission Matters

Most policies extend coverage to drivers who have your permission to use the vehicle. If someone takes your car without permission, coverage may be affected or denied.

Excluded Drivers

Some policies specifically exclude certain drivers. If an excluded driver gets behind the wheel and causes an accident, the insurance company may not cover the claim.

Household Drivers Should Be Listed

If someone in your household regularly drives your vehicle, they should be listed on your policy. Failing to disclose regular drivers could create issues if a claim occurs.

Business or Ride-Share Use

Using your personal vehicle for business purposes, food delivery, or ride-sharing services may require additional coverage. Standard personal auto policies don’t always cover these activities.

Before Lending Your Vehicle

Before handing over your keys, consider:

✅ Does the person have a valid driver’s license?
✅ Do they have a safe driving history?
✅ Are your liability limits sufficient?
✅ Does your policy have any driver restrictions?

A quick review now can prevent major headaches later.

We’re Here to Help

At Carolina Property Insurance, we help drivers across Murrells Inlet, Georgetown County, Horry County, and the Grand Strand understand their coverage and make confident insurance decisions.

Whether you need auto, home, flood, condo, renters, boat, motorcycle, umbrella, or business insurance, our local team can help you find coverage that fits your needs and budget.

📞 Have questions about your auto policy or wondering if you have the right coverage? Contact Carolina Property Insurance today for a policy review or free quote. We’re here to help protect what matters most.

What Additional Insured Endorsements Really Mean for Businesses

Additional insured endorsements are a common part of business contracts—but they’re also one of the most misunderstood. Without a clear understanding, businesses can run into unexpected liability, coverage gaps, or even disputes when a claim arises.
 
At Carolina Property Insurance, we regularly help clients navigate these requirements—especially here in Myrtle Beach, Murrells Inlet, and the surrounding areas, where business relationships and contracts can get complex. Understanding how these endorsements work can make a big difference in protecting your business.

What Is an Additional Insured Endorsement?
An additional insured endorsement is a change to a liability insurance policy that extends limited protection to a third party.
In simple terms, it allows one business to be covered under another business’s liability policy—but only under specific circumstances tied to the named insured’s work, services, or operations.
You’ll typically see these endorsements required in agreements such as:
  • Landlord and tenant relationships
  • Property management and vendor contracts
  • Construction projects between owners and contractors
  • General contractor and subcontractor agreements
  • Vendors providing on-site services or event support
In each case, the goal is to provide protection for claims arising from one party’s work—not for unrelated actions.

Why Businesses Use Additional Insured Endorsements
These endorsements are designed to help manage shared risk.
 
For example, a property owner may require a contractor to add them as an additional insured before starting work. If the contractor’s work causes damage or injury, the owner may seek coverage under the contractor’s policy.
 
The same principle applies to vendors, tenants, and subcontractors—when one party’s work could create exposure for another, this endorsement helps provide a layer of shared protection.

How This Coverage Works in Real Situations
When properly in place, an additional insured may request coverage under the named insured’s liability policy if a claim is directly tied to that party’s work.
Here are a few common examples:
  • A subcontractor performs faulty work that leads to property damage. The general contractor is pulled into the claim and looks to the subcontractor’s policy.
  • A tenant’s business operations result in an injury on the property. The landlord may rely on the tenant’s liability coverage.
  • A vendor damages property while performing services, and the hiring business is named in the claim. Coverage may apply under the vendor’s policy.
The key takeaway: coverage applies only when the claim stems from the named insured’s work—not from the additional insured’s independent actions.

What Additional Insured Endorsements Do Not Cover
It’s important to understand what these endorsements don’t do.
They do not:
  • Provide the same level of coverage as a named insured
  • Cover every claim involving the additional insured
  • Replace the need for your own liability insurance
  • Protect against your own independent negligence
  • Automatically satisfy all contract requirements
Because coverage is limited, every business should still carry its own liability insurance to protect against its own risks.

Why Certificates of Insurance Can Be Misleading
Certificates of insurance (COIs) are often used to show proof of coverage—but they don’t actually create or change coverage. Even if a certificate mentions additional insured status, the endorsement must be properly issued and included in the policy.
 
In short: the policy—and the endorsement wording—controls the coverage, not the certificate.

Why Contract Review Matters
Additional insured endorsements may seem routine, but the details matter.
Before signing any lease, vendor agreement, or construction contract, it’s important to review:
  • What coverage the contract requires
  • Whether your current policy meets those requirements
  • Whether endorsements need to be added or adjusted
Taking a little time upfront can help prevent costly surprises later.

A Smart Way to Manage Shared Risk
Additional insured endorsements are a valuable tool for managing risk when businesses work together—but they’re not a complete solution on their own. Understanding how they work—and where their limitations are—can help you make better decisions and avoid unexpected financial exposure.

Let’s Make Sure You’re Set Up Correctly
If your business operates in Myrtle Beach, Murrells Inlet, or the surrounding areas and you’re unsure whether your coverage meets contract requirements, we’re here to help.
 
We’re happy to review your policies, walk through your contracts, and make sure you have the right protection in place—so you can move forward with confidence.
Feel free to reach out anytime—we’re here to support you and your business.

Cyber Insurance for Modern Businesses

Cyber threats are no longer just an IT concern—they are a real business risk. Today’s attacks can impact your revenue, disrupt daily operations, and damage customer trust. As digital risks continue to grow, many businesses are adding cyber insurance as part of a well-rounded protection strategy.
Here’s a simple look at why cyber coverage matters and how it can help protect your business—especially here in Myrtle Beach and across the Grand Strand, where so many businesses rely on technology every day.

Why Cyber Threats Are on the Rise
Cybercriminals have evolved. Instead of targeting one business at a time, they now use automated tools to scan for vulnerabilities and attack multiple organizations at once.
One of the most common threats is phishing. These emails often look like they’re coming from a trusted source—such as your bank, a vendor, or even a coworker—and are designed to trick employees into sharing sensitive data or approving fraudulent payments.
For businesses of all sizes, especially those without extensive IT support, these attacks can be surprisingly easy to fall for.

The Real Cost of a Cyber Incident
Even one cyber event can create significant financial strain. Costs often go well beyond fixing the issue and may include:
  • Digital forensics to understand what happened
  • Legal and compliance requirements
  • Customer notifications and credit monitoring services
  • Public relations efforts to rebuild trust
  • Lost income due to downtime or system outages
Even smaller incidents can turn into expensive, layered challenges very quickly.

Common Cyber Risks Businesses Face
Today’s businesses are exposed to a wide range of cyber risks, including:
  • Ransomware attacks
  • Phishing and payment fraud
  • Data breaches involving customer or employee information
Another growing concern is vendor-related disruption. Many businesses here along the coast rely on cloud-based systems, payment processors, and third-party software. If one of those providers goes down, it can interrupt your operations—even if your own systems are secure.

What Cyber Insurance Typically Covers
Cyber insurance is designed to help your business handle both the immediate impact of an incident and the aftermath.
Coverage may include:
  • Incident response and forensic investigations
  • Data restoration and system recovery
  • Lost income during covered downtime
  • Legal defense and regulatory compliance support
  • Customer notification and identity protection services
Having these resources in place can make a stressful situation much more manageable.

Why Traditional Policies Aren’t Enough
Many business owners assume their existing insurance policies will cover cyber incidents—but that’s usually not the case.
  • General liability often excludes electronic data issues
  • Property insurance typically doesn’t cover cyberattacks
  • Crime policies may offer limited protection, but often leave gaps
A dedicated cyber policy helps fill those gaps and provides more complete protection in today’s digital environment.

What to Look for in a Cyber Policy
Cyber policies can vary quite a bit, so it’s important to understand what you’re getting. Key features to review include:
  • Business interruption coverage: What qualifies as a disruption?
  • Social engineering protection: Coverage for fraudulent emails or payment scams
  • Vendor disruption coverage: Protection if a third-party provider goes down
  • Access to experts: Immediate help from forensic, legal, and PR professionals
The right policy doesn’t just provide coverage—it provides support when you need it most.

Building a More Prepared Business
Cyber risks are increasing in frequency, complexity, and cost. Businesses that rely only on standard policies may face serious coverage gaps.
A dedicated cyber insurance policy can help protect your financial stability, support your recovery, and give you peace of mind knowing you’re prepared for the unexpected.

Let’s Make Sure You’re Covered
If you’re a business owner in Myrtle Beach or the surrounding areas and aren’t sure how your current insurance would respond to a cyber event, now is a great time to take a closer look.
 
We’re always happy to walk through your coverage, answer questions, and help you understand where you’re protected—and where there may be gaps. Feel free to reach out anytime. We’re here to help you protect what you’ve worked so hard to build.

Essential Insurance Questions Small Business Owners Ask

What Affects the Cost of Small Business Insurance?
Short answer: it depends on your business.
Every business in the Myrtle Beach area is a little different, and your insurance price reflects that. A few of the biggest factors include:
  • What you own (equipment, inventory, tools, etc.)
  • How many employees you have
  • The type of work you do
  • The coverage limits and deductibles you choose
For example, a boutique in downtown Myrtle Beach will have very different risks than a contractor working jobs from Conway to Murrells Inlet. Insurance companies look at all of this to figure out your level of risk—and that’s what shapes your premium.

Do Home-Based or One-Person Businesses Really Need Insurance?
They do—and this surprises a lot of people.
Even if you’re running a small business from home or it’s just you, things can still go wrong. Someone could get hurt, equipment could get damaged, or a client issue could turn into a claim.
A lot of people assume their homeowners insurance has them covered, but in most cases, business activity is only covered in a very limited way. Having a simple general liability policy can go a long way in protecting you.

What Types of Coverage Do Most Small Businesses Start With?
This depends on your business, but we see a lot of Myrtle Beach–area businesses start with a few key basics:
  • General Liability – Covers injuries or property damage claims
  • Commercial Property – Protects your building, tools, inventory, and equipment
  • Workers’ Compensation – Usually required once you hire employees
These cover a lot of the everyday risks that come up across different industries around the Grand Strand.

What’s a BOP (Business Owner’s Policy)?
You’ll probably hear this term come up a lot.
Business Owner’s Policy (BOP) bundles general liability and commercial property into one policy. It’s often more affordable than buying them separately, which is why so many small businesses in Myrtle Beach and nearby areas go this route.
It’s simple, cost-effective, and works really well for many businesses—though some higher-risk operations may need something a little more customized.

Do I Need Commercial Auto Insurance?
If you use a vehicle for your business—even here and there—it’s worth a closer look.
That includes things like:
  • Driving to meet clients around Myrtle Beach or North Myrtle Beach
  • Running deliveries
  • Hauling tools or equipment between jobs
Most personal auto policies don’t cover business use, so it’s important to make sure you’re not caught off guard if something happens.

What Happens If I Don’t Have Enough Coverage?
This is where things can get tough.
Without the right coverage in place, even one claim can turn into a big financial hit. That could mean paying out of pocket for things like:
  • Legal costs
  • Medical bills
  • Repairs or replacements
  • Lost income if your business has to pause
  • Fines for not having required coverage
Having the right insurance isn’t just about checking a box—it’s about making sure your business can keep going if something unexpected happens.

Is There a Way to Keep Insurance Costs Down?
Absolutely—and it doesn’t mean cutting corners.
Here are a few simple ways business owners around the Grand Strand manage costs:
  • Review your coverage every year as your business grows
  • Talk with your agent about deductibles and options
  • Bundle policies when possible, to get discounts
A quick check-in once a year can make a bigger difference than most people expect.

Final Thoughts
Owning a business in Myrtle Beach and the surrounding areas is exciting—but it also comes with real responsibility. The good news is that insurance doesn’t have to be complicated. When you understand your risks and have the right coverage in place, you can focus on what you do best running and growing your business. And if you ever feel unsure, having a local agent who understands the area, the risks, and your goals can make the whole process a lot easier.

3 Things You Should Check on Your Policy Today

Have you ever thought about what is most important in your homeowner’s insurance policy? If you want to understand your home insurance policy, it’s important to make sure you have the coverage you really need. There are three main areas of your policy to focus on for comprehensive protection for your property. Comprehensive protection in an insurance policy is when you are insured against a wide range of risks and unforeseen events, adequately. 

# 1. Coverage Types

– Dwelling Coverage: Make 100% sure that your policy has the full replacement cost of your home as well as all structures on your property, even your fencing! Your agent can help you determine the cost to rebuild your home in today’s market by running a quick replacement cost estimate. 

– Personal Property Coverage: Is your policy limit too low or too high? We see this a lot in today’s market, sometimes the limit is preset by companies you may be overinsured. Why pay for more than what you own? You may need a separate policy called an inland marine policy to schedule valuables such as jewelry, guns and collectibles. Never assume everything you own is covered, most policies have preset limitations on specific valuables. 

– Liability Coverage: it is imperative to have enough liability protection/limits in case someone is injured on your property or if you accidentally cause damage to someone else’s property. No one likes getting sued, but it happens daily. 

# 2. Deductibles

– Amounts:  In coastal SC, almost every company sets a minimum amount on your wind/hail deductible and that is normally 2% of your dwelling coverage. All other peril deductibles (anything not related to wind/hail) can range from $1,000-$5,000 or a percentage of dwelling coverage. You can pick which deductible is most affordable to you. But remember, you pay those deductibles out-of-pocket before insurance kicks in. Choose an amount that fits your financial situation.

# 3. Exclusions and Limitations

– Specific Exclusions: In our area, flood damage is specifically excluded on property policies. Be aware of what is not covered under your policy and don’t just assume you have coverage. Read through your policy to see the exclusions.

– Coverage Limits: A lot of policies have caps on damages caused by water on older homes. See if your policy has any caps on specific types of claims, like theft or damage to personal property. This also ties back to valuables and realizing there are certain limits built into policies. 

    Our homes are our livelihoods. Please ensure that you understand your policy. No one thinks the unimaginable could happen to them, but we see it more than you know. In the event of a total loss, you will need the tools necessary to help yourself recover financially. Reviewing these three areas on your policy does just that! 

Submitted by Mary Beth Morris

Did you know…?

Did you know that fewer than 4% of members of Congress come from an insurance background?  

The numbers are similarly low in the South Carolina State Legislature. By comparison, many elected officials come from legal backgrounds, and a significant number serve on insurance and banking committees at both the state and national levels. That gap says a lot about why broader professional representation matters—especially when legislation affects so many different stakeholders.

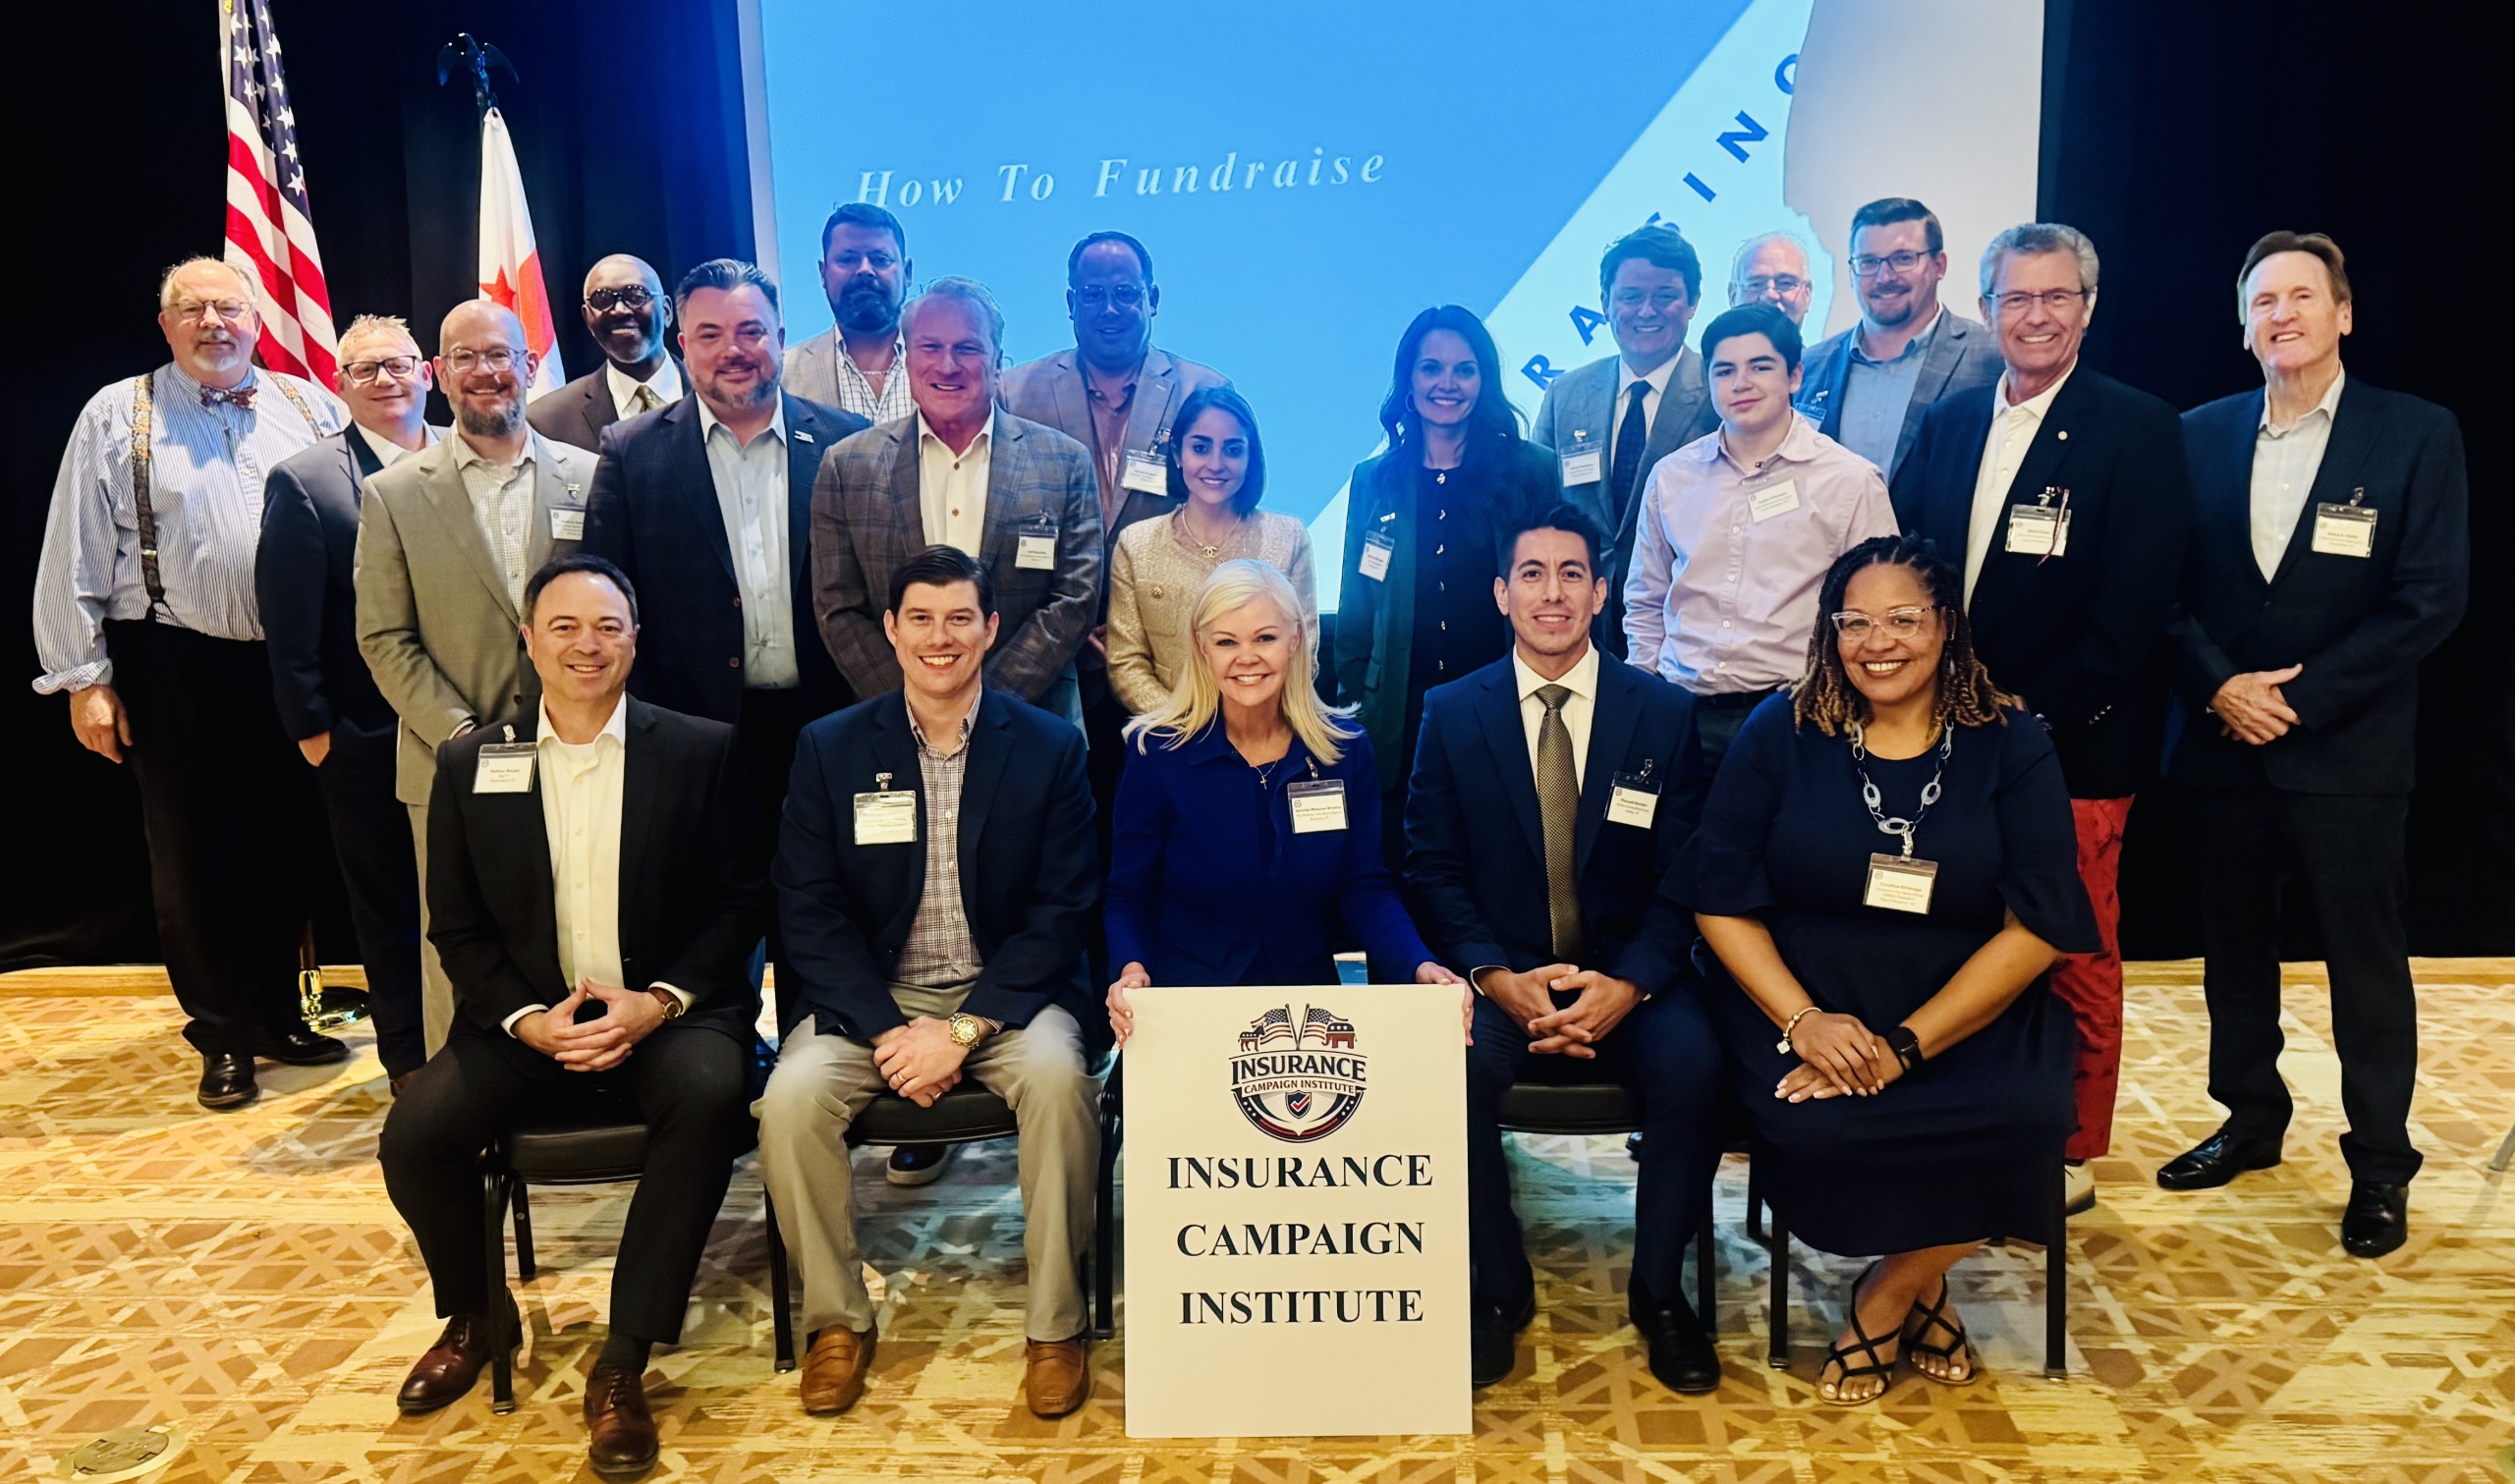
That is exactly why The Big “I” (the Association of Independent Insurance Agents) created the Insurance Campaign Institute, held this past April in Washington, DC. I had the privilege of attending this inaugural event alongside 25 other insurance professionals from across the country. Throughout the day, we heard from and engaged with a variety of speakers, including elected officials and political consultants, who shared valuable insight into what someone like me would need to think through if I ever decided to run for public office.

What made this event especially meaningful was that it did more than simply encourage insurance professionals to get involved in the legislative process. It also provided practical guidance on how to run a successful campaign and how to contribute in a more informed and effective way to insurance regulation and public policy.

The Big “I” plans to continue this program for years to come, and I believe that is a good thing for both the industry and the public. The more insurance professionals who are willing to step up and serve, the better the chances of shaping regulatory laws that are balanced, informed, and responsive to the needs of consumers, carriers, legal professionals, and the communities they all serve.

Below is a short video created by the Big I with highlights of the event:

I have also included a link for an article that was published in IA Magazine about the 2026 Insurance Campaign Institute:

Insurance Campaign Institute Prepares Agents to Step Up for Public Office – IA Magazine

Submitted by Micah Witherspoon

E-Bikes and E-Scooters: What you need to know

Electric bikes, electric scooters and low-speed vehicles (LSVs) are growing in popularity. Between 2018 and 2022, which is the latest available data, sales of e-bikes rose from approximately 250,000 per year to more than one million, while the rentals of both e-bikes and e-scooters also increased dramatically, according to the National Association of City Transportation Officials (NACTO).

As the use of these personal micromobility devices (PMDs)—defined as lightweight, micro-sized vehicles with limited power and speed, used over short distances—continues to grow and evolve, emergency rooms are seeing many more people injured while riding e-bikes and e-scooters.

While e-bikes and e-scooters offer a convenient and eco-friendly mode of transportation, there are downsides to their use, with more than 20,000 people injured each year while riding an e-bike and approximately 3,000 requiring hospitalization, according to the American College of Surgeons.

The growing popularity of these devices also presents carriers with liability challenges. “E-bikes and scooters are increasingly popular, and many models now reach speeds comparable to mopeds,” says Laurel Page, assistant vice president, recreational product management, American Modern, a Munich Re company. “These vehicles present unique risks, including severe accidents, theft and battery-related fires.”

Crucially, “most homeowners and renters policies exclude motorized vehicles, leaving significant coverage gaps,” she says. For agents, this presents an opportunity to work with carriers and clients to bridge the knowledge gap and ensure their clients have the necessary coverage or are aware of the exposure.

“Customers may not immediately think about e-bikes, dirt bikes or scooters when discussing their insurance needs, so, as a first step, agents should ask about ownership of any of these types of vehicles,” says Scott Hall, motorcycle product manager at Progressive Insurance. “That simple question can open the door to a meaningful conversation about why coverage matters, highlighting liability risks, potential financial impact from an accident and the protection insurance can provide if the vehicle is stolen or damaged.”

As usage increases, the concern is that many users are unaware of the risks and potential gaps in coverage. “In reality, homeowners policies often exclude motorized vehicles or provide limited coverage only while the vehicle is on the insured property, and the policy may indicate a sublimit for e-bikes,” Hall says. “Even when coverage does apply, homeowners should consider the potential impact to their premium if they file a claim related to an e-bike.”

“Consumer misunderstanding can lead to two problems: owners either go uninsured or mistakenly believe they’re protected, only to face unexpected gaps and financial consequences later,” Hall continues. “Agents can play an important role in educating consumers on available coverages under existing policies, any limitations and the benefits of a standalone policy.”

As trusted advisors, agents can explain why homeowners and auto policies don’t adequately protect e-bikes, scooters, golf carts and dirt bikes.

These include highlighting “the problems one might see on an endorsed homeowners policy, excluding guest passenger liability and uninsured or underinsured motorists’ coverage. These are auto coverages recreational vehicle owners might expect to have,” says Eric Uturo, product manager, Foremost – a Farmers Insurance Company. “A recreational vehicle insurance policy from an insurer specializing in this type of insurance can help customers avoid potential coverage gaps.”

Additionally, “these products have many small manufacturers and parts producers, which can cause complexity for non-specialized insurer claim departments,” Uturo says. They can also “promote standalone policies that offer dedicated protection for liability, damage and theft without impacting homeowner policy claims, as well as comparing multiple carriers to deliver the best combination of coverage and price, reinforcing their role as a trusted advisor,” Page says.

Additionally, by keeping up to date on technological changes within the market, as well as the changing rules and regulations around e-bikes, e-scooters and LSVs, agents can help alleviate carrier concerns when it comes to scenarios, such as “misclassification” by “treating motorized bikes or scooters as standard bicycles—leading to inconsistent underwriting and unrecognized risk,” Page says.

Identifying and highlighting risks, such as “high-speed models increasing injury severity, expensive components and lithium-ion batteries introducing fire hazards that require specialized coverage, as well as varying state regulations creating complexity and uncertainty in policy design,” Page says, can add to the valuable role agents play for both carriers and their clients.

Submitted by: Big I Independent Agents